8 Behavioral Interview Questions Finance Candidates Must Know
TL;DR
Behavioral questions represent roughly 30–50% of finance interviews — and closer to 60–66% at firms like Goldman Sachs and J.P. Morgan investment banking. The eight questions above test accuracy, judgment, prioritization, communication, ownership, adaptability, and integrity through real examples rather than personality claims. Use STAR as a compression tool, not a script: the Action section should carry the most weight, and results should be quantified only when the figure is verified. The strongest answers show prioritization logic instead of long hours, make control decisions visible instead of just describing outcomes, respect process owners instead of claiming credit for fixing what nobody else handled, and connect every mistake to the specific check that now prevents it. Tailor evidence to the role — investment banking rewards deal-team coordination and review discipline, corporate finance rewards reporting integrity, FP&A rewards forecast assumption testing, and asset management rewards data integrity and client-facing escalation. Build two or three flexible stories that each carry multiple types of evidence rather than memorizing eight separate speeches.
You know the technical work. You can explain a variance, build a forecast, reconcile a balance, or discuss a valuation method. Then an interviewer asks, “Tell me about a time you challenged an assumption,” and the answer disappears into a vague story about teamwork.
That gap costs candidates offers. Strong behavioral answers connect a specific situation to the decision you made, the result you produced, the stakeholders you managed, and what you learned. In finance, interviewers aren't listening for polished personality statements. They're looking for evidence of accuracy, judgment, prioritization, communication, ownership, adaptability, and integrity.
Behavioral questions are a major part of finance interviews. One investment-banking guide estimates they represent roughly 30–50% of interviews (IBFlash's behavioral interview guide). Other market guidance places Goldman Sachs interviews at about 60% behavioral and J.P. Morgan investment-banking interviews at about 66% behavioral, based on 107 J.P. Morgan candidate reports collected from 2016 to 2022 (the same finance interview analysis).
Use the STAR structure, Situation, Task, Action, Result, as a compression tool, not a script. Build authentic examples from internships, coursework, part-time work, or prior roles, then adapt the emphasis to investment banking, corporate finance, FP&A, or asset management. For broader preparation, these senior professional job interview tips can help you sharpen your delivery.
What Are the Most Common Behavioral Interview Questions in Finance?
Finance interviewers aren't listening for polished personality statements. They're looking for evidence of accuracy, judgment, prioritization, communication, ownership, adaptability, and integrity. And these questions carry real weight — one investment-banking guide estimates behavioral questions represent roughly 30–50% of interviews, with Goldman Sachs interviews around 60% behavioral and J.P. Morgan investment-banking interviews around 66% behavioral based on 107 candidate reports collected from 2016 to 2022.
The eight behavioral interview questions finance candidates face most often:
1. Tell me about a time you had to meet a tight deadline in a financial analysis project. Show prioritization logic, not exhaustion. Rank the highest-risk balances first, protect accuracy with specific checks, and communicate the trade-off before the deadline becomes a crisis.
2. Describe a situation where you found an error in financial data or reported information. Make the control logic visible — distinguish a timing difference from a real error, name the supporting document that triggered your review, and describe the review step you added afterward.
3. Tell me about a time you disagreed with a manager or senior colleague on a financial decision. Bring evidence, not ego. Show you understood their commercial reasoning first, then present the comparison, sensitivity analysis, or contract terms that justified another look.
4. Give an example of when you had to learn a new financial skill or tool quickly. Connect the skill to the business problem it solved, name your learning method, explain how you validated the output before others relied on it, and state the boundary of your proficiency honestly.
5. Describe a time you communicated complex financial information to a non-financial audience. Translate, don't dilute. Identify what the audience needed to decide, build a bridge (timeline, waterfall, plain-language comparison), and check comprehension.
6. Tell me about a time you owned a problem that wasn't technically your responsibility. Show the consequence, the permission you obtained from the process owner, your defined contribution, and what stayed with the other team.
7. Describe a time you made a mistake in your financial work and how you handled it. Choose something real, contained, and recoverable. Own the action without blaming the system, escalate promptly, and name the control that now catches it.
8. Tell me about a time you had to balance competing priorities or stakeholder requests. Never say "I worked on everything at once." Explain what you deferred, why, and how you protected quality on the highest-consequence work.
1. Tell Me About a Time You Had to Meet a Tight Deadline in a Financial Analysis Project
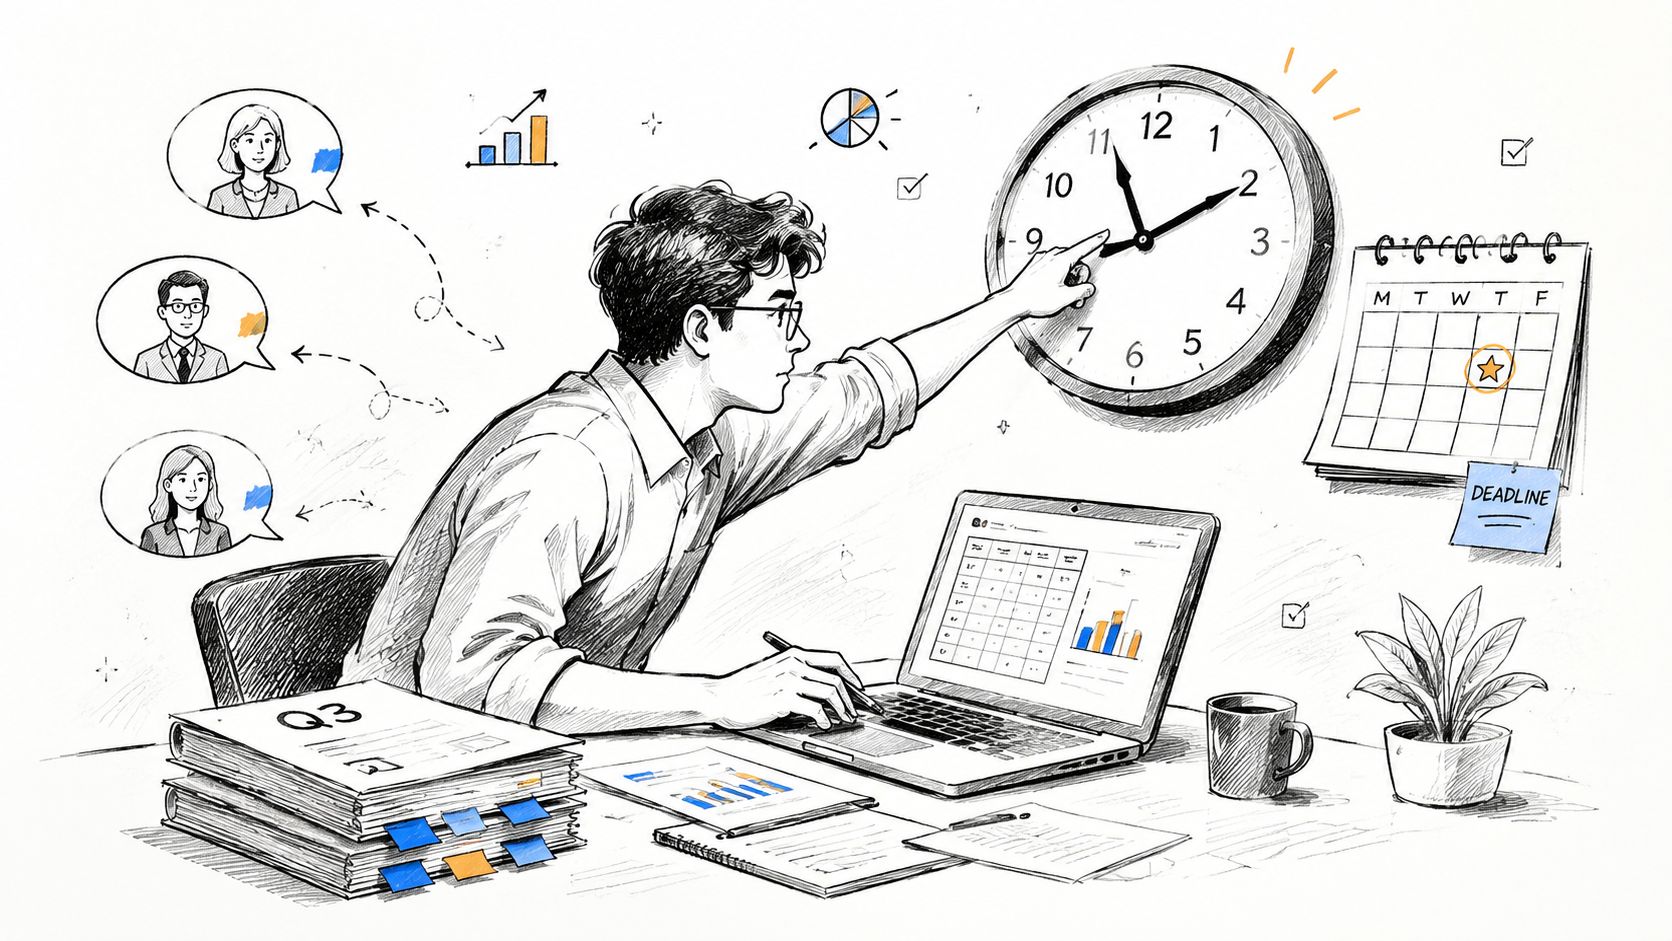
A strong answer starts with the constraint. “I worked hard” doesn't tell an interviewer how you prioritize risk, protect quality, or communicate when the timeline is fixed. Finance deadlines often come from external audits, market closures, earnings releases, board meetings, or regulatory filings, so the useful evidence is your decision process under pressure.
Consider an intercompany reconciliation assigned shortly before an external audit. The standard process would take longer than the available window. A credible STAR answer would explain that you identified the largest and highest-risk balances first, divided the remaining work systematically with a junior analyst, and gave the audit partner a concise summary of what had been resolved and what still required review. The strength of that answer isn't the late nights. It's the prioritization logic and the fact that communication happened before the deadline became a crisis.
A month-end close example can work equally well. If a system migration moved the cutoff forward, explain how you flagged the change, proposed a controlled manual workaround, and validated material transactions using backup reports. Don't claim perfection if you didn't maintain documentation. In finance, an undocumented shortcut can create more risk than a visible delay.
What the interviewer needs to hear
Show the sequence of decisions rather than narrating every task:
- Define the deadline: State what had to be delivered and why the date couldn't move.
- Rank the risk: Explain which accounts, transactions, or outputs you reviewed first.
- Protect accuracy: Describe the checks that prevented speed from becoming careless work.
- Manage stakeholders: Say who you updated, what trade-off you explained, and when.
- Close with learning: Identify what the experience taught you about working under pressure.
Practical rule: Don't present exhaustion as the achievement. Present a defensible prioritization method, transparent escalation, and a reliable control.
For investment banking, emphasize deal-team coordination and fixed deliverables. For FP&A, focus on decision-useful analysis delivered despite incomplete inputs. For corporate finance or asset management, show how you protected data quality while serving a time-sensitive request. A useful interview preparation guide can help you turn the example into a short, resume-grounded response instead of memorizing a paragraph.
2. Describe a Situation Where You Found an Error in Financial Data or Reported Information
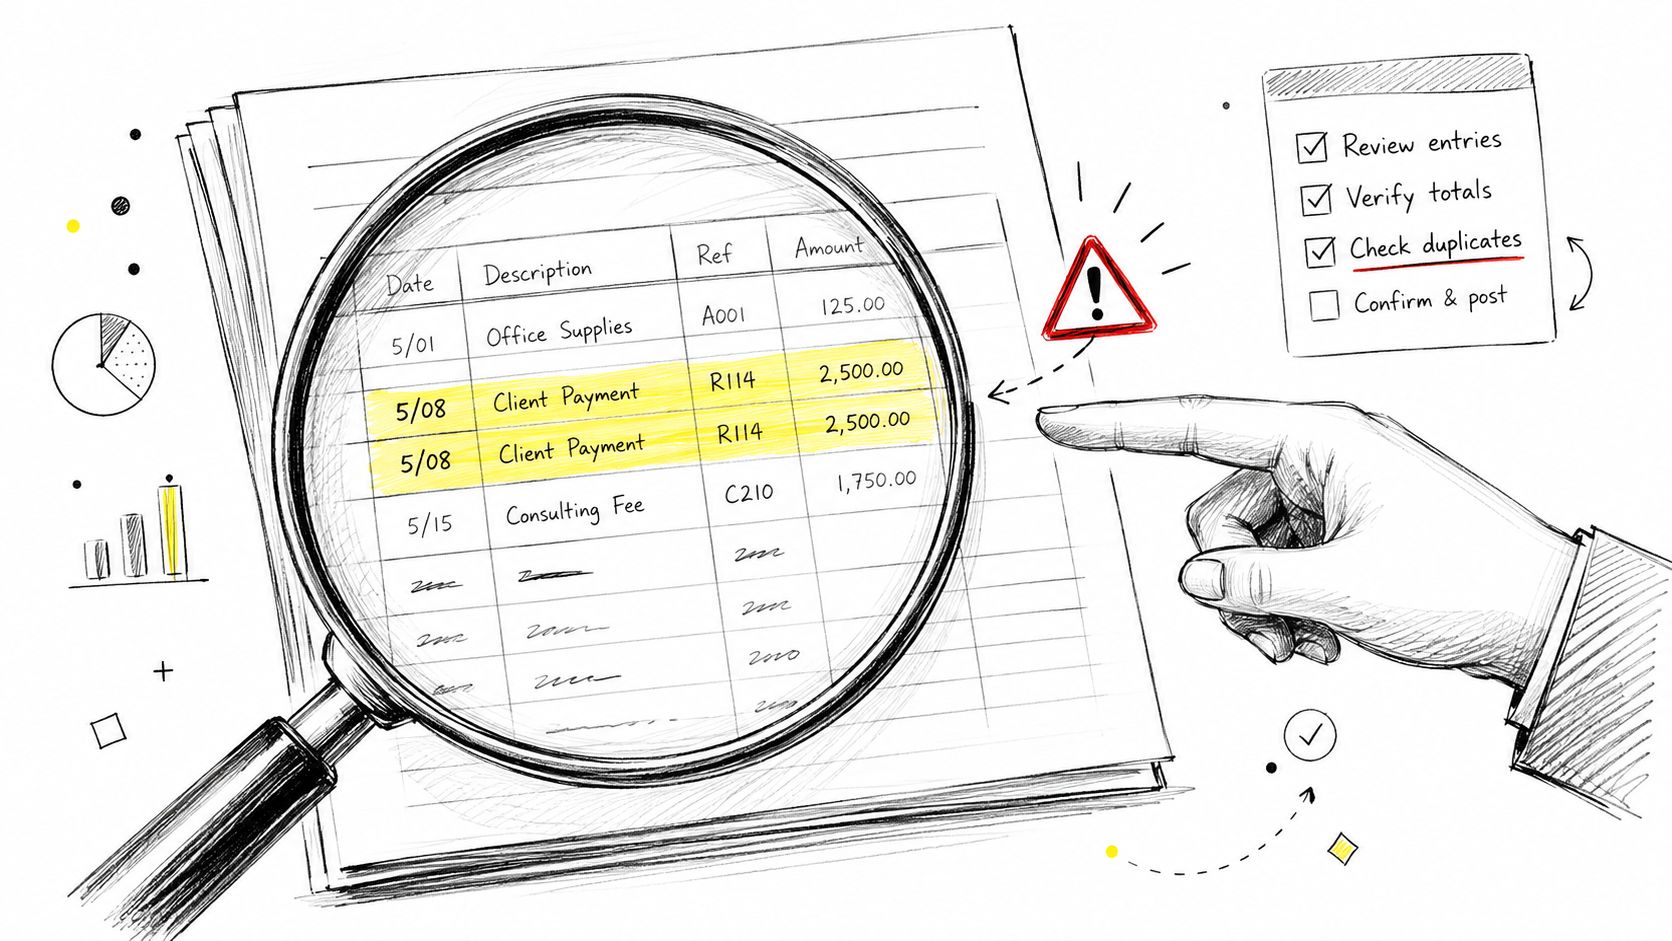
A reconciliation that fails to tie tests more than attention to detail. It tests whether you can investigate without blaming the preparer, distinguish a timing issue from a real error, and explain the business consequence clearly.
For example, a monthly expense reconciliation may not match the underlying credit card statement. Trace the variance to original receipts, identify a duplicate entry, and show the finance manager the affected records. Explain how you separated the timing difference from the duplication, corrected the report, and confirmed the figures before controller review.
Your answer should make the control logic visible. If you recommended a second-level review for higher-value reimbursements, connect that change to reporting accuracy, cash management, or stakeholder trust. The purpose was targeted scrutiny where an error could matter, not extra bureaucracy for every transaction.
Use the investigation as the structure of your story, but vary the detail according to the finance role:
- Investment banking: Explain how you checked a model input, transaction schedule, or client data set before it reached a deal team or senior reviewer. Show how you protected the deliverable while keeping the team informed.
- Corporate finance: Focus on a variance in expenses, cash activity, or management reporting. State how you confirmed the source and prevented the issue from influencing a decision.
- FP&A: Show how you tested an unexpected movement in a forecast or budget file, especially when business partners supplied incomplete or inconsistent inputs.
- Asset management: Emphasize data integrity, valuation or performance reporting, and the escalation path when an exception could affect client communication.
A concise STAR answer should identify what failed to reconcile, name the comparison or supporting document that triggered your review, and describe the checks that ruled out a simple timing difference. Then state whom you informed, what evidence you presented, and how the report or process changed.
Avoid two weak extremes. Treating the error as trivial makes the example forgettable, while portraying colleagues as reckless raises concerns about judgment. Credibility comes from precise verification, neutral communication, and an outcome you can measure, such as a corrected report, a documented review step, or clearer ownership.
Use practice interview questions to rehearse the sequence without memorizing wording. You should be able to explain the issue, investigation, escalation, and result in a focused response.
3. Tell Me About a Time You Disagreed with a Manager or Senior Colleague on a Financial Decision
A senior manager proposes lowering an allowance after one strong quarter of collections. You see a short-term improvement, not yet a reliable trend. This creates a useful interview example because the disagreement concerns evidence, risk, and how to support a decision after review.
Explain the decision context first. State the assumption your manager wanted to use, the risk you identified, and the comparison you prepared. A longer historical view, sensitivity analysis, or scenario comparison can show why the proposed change deserved another look. A strong STAR answer makes clear that you understood the manager's reasoning before presenting your concern.
Your evidence should match the finance role:
- Investment banking: Compare valuation assumptions, transaction analysis, or a client-facing output with the supporting model and deal information.
- Corporate finance: Test the effect of forecast methodology or scenario selection on cash flow, earnings, or management guidance.
- FP&A: Show how you challenged an operating assumption, checked business-partner inputs, and separated a temporary variance from a change in run rate.
- Asset management: Explain how you questioned an investment thesis, risk interpretation, or data-quality issue before it affected portfolio commentary or client reporting.
If the issue involves accounting treatment, document the analysis rather than relying on a verbal objection. Refer to the contract terms, the applicable framework, and the reporting implication. Then describe the meeting where you walked through the comparison. The outcome may be a revised treatment, an agreed monitoring step, or a decision to retain the original approach with clearer documentation.
Use language that keeps the discussion factual:
- “I understood the commercial reason for the original assumption.”
- “My concern was the evidence supporting the reporting conclusion.”
- “I compared the proposed treatment with the contract terms and relevant guidance.”
- “We agreed on the points requiring review and documented the final rationale.”
- “I supported the decision once the analysis and controls were clear.”
The trade-off is judgment. Challenge a decision when the evidence is weak, the risk is material, compliance may be affected, or stakeholders could receive a misleading conclusion. Avoid turning the story into a criticism of the senior colleague. Interviewers want to see respectful escalation, precise analysis, and ownership of the final outcome.
A useful practice routine is to browse leadership development prompts and rehearse the evidence, conversation, decision, and result without memorizing a script.
“Bring evidence, not ego. The objective is a better decision, not a personal victory.”
4. Give an Example of When You Had to Learn a New Financial Skill or Tool Quickly
A new tool matters only when it solves a finance problem. In an interview, connect the skill to the work it improved, the controls you applied, and the result. Saying you learned SQL, Python, Power BI, or a proprietary revenue platform is weaker than showing why the team needed it and what changed afterward.
Suppose a finance team relied on IT for transaction extracts. A strong story might cover structured SQL practice, simple queries in a safe environment, and a production query for customer payment history. Explain whether the skill reduced manual data pulls or gave analysts faster access to information. If complex joins were still outside your ability, state that boundary. Accurate self-assessment carries more weight than inflated proficiency.
A proprietary revenue-recognition system creates a different test of judgment. Describe how you reviewed the documentation, checked the required CSV format, built an Excel mapping template, tested it against historical data, and asked a vendor or manager to review the process. The evidence shows adaptability and ownership while recognizing that self-study does not replace finance controls.
Make the learning auditable
Build the answer around the work rather than a generic list of courses:
- Business trigger: Identify what was blocked, slow, manual, or unreliable.
- Learning method: Name the documentation, course, colleague, test environment, or practice data you used.
- Validation: Explain how you checked the output before others relied on it.
- Practical impact: State which process, analysis, or decision improved.
The emphasis should match the finance role. FP&A candidates can focus on reporting automation, data modeling, or scenario analysis. Investment-banking candidates can show how they learned a new financial model or data source under transaction pressure. Corporate finance examples may involve enterprise systems and planning workflows. Asset-management candidates can discuss research tools, portfolio analytics, or investment-monitoring processes.
A concise STAR answer should include a measurable result where the experience supports one, such as fewer manual steps, quicker reporting access, or a cleaner review process. Keep the claim proportionate to the evidence.
Independent learning earns credibility when paired with review. Explain what you tested yourself, what you escalated, and how the second check protected the analysis or decision. Finance interviewers are assessing adaptability and judgment together, not speed in isolation.
5. Describe a Time When You Had to Communicate Complex Financial Information to a Non-Financial Audience
A finance professional can be technically correct and still fail if the audience doesn't understand what to do next. This question tests whether you can translate financial information without distorting it.
An operations team might wonder why its bonus pool increased while revenue remained flat. A strong answer would explain that you recognized the team cared about how its work affected compensation, not about a technical definition of operating efficiency. You then created a simple visual connecting revenue, operating costs, efficiency, and the bonus calculation. The result was useful because the operations manager could explain the logic to the wider team.
For an FP&A example, you might present cash constraints to HR during a hiring discussion. Instead of displaying every line in a cash-flow report, map the timing of the current balance, expected customer receipts, normal operating costs, and seasonal supplier payments. Then explain the point at which cash becomes tight and how long the constraint lasts. The audience doesn't need less truth. It needs the truth organized around its decision.
Translate, don't dilute
Start by identifying what the audience knows and what it needs to decide. Then remove jargon that doesn't change the decision, preserve assumptions that do matter, and use a visual or example to make the relationship clear.
- Name the audience: Operations, HR, legal, sales, executives, or clients.
- Define the decision: What did they need to approve, change, or communicate?
- Choose the bridge: Use a timeline, waterfall, chart, or plain-language comparison.
- Check comprehension: Invite questions and ask the stakeholder to explain the implication in their own terms.
- Measure usefulness: Explain what decision moved forward or what confusion stopped.
Your tone matters. Don't say you “dumbed down” finance. You adapted the message to respect the audience's expertise in its own area. That distinction is especially important in client-facing asset management and in banking roles where senior stakeholders need concise, decision-ready analysis.
If nerves make it difficult to keep answers concise, an AI interview coach can help you review pacing, filler words, and answer length during practice.
6. Tell Me About a Time You Owned a Problem That Wasn't Technically Your Responsibility
Ownership in finance means addressing a business risk while respecting the team that formally owns the process. The strongest answer shows that you identified the consequence, consulted the right person, contributed a defined piece of work, and kept decision rights clear.
In FP&A, repeated collections shortfalls can weaken the cash forecast. Explain how you raised the issue with the accounts-receivable manager, asked permission to help diagnose it, and reviewed how the credit policy affected customer disputes. You might then identify the customer segments involved and propose a controlled test of a revised approval process. The evidence is your judgment: you supported the process owner instead of criticizing the team or changing policy without approval.
A treasury example can focus on inconsistent daily cash inputs from several departments. After confirming that treasury owned consolidation, you could standardize the submission format, compile the information, and deliver it at an agreed time. Once the process produced reliable inputs, you could present it to the treasurer for formal adoption. That sequence demonstrates initiative, governance, and attention to the team's result.
Use the story to make ownership boundaries explicit:
- Business consequence: Link the issue to cash, forecasting, reporting, client service, or a decision that could be delayed.
- Permission and coordination: Name the process owner and explain what you confirmed before taking action.
- Defined contribution: Specify whether you built an analysis, template, test, control, or coordination process.
- Accountability: State what you owned and what remained with the other team.
- Result: Describe the improvement for colleagues, customers, or decision-makers, using a measurable outcome when your experience supports one.
Avoid saying, “I fixed a problem nobody else was handling.” That framing can sound territorial and may suggest weak collaboration. Say instead, “I identified a risk affecting our output, asked how I could help, and built a solution with the owner.” Keep the answer factual, especially when the result was process improvement rather than a dramatic rescue.
Tailor the evidence to the role. In asset management, you could help resolve inconsistent company data used in research. In corporate finance, you might support treasury or procurement. In investment banking, you may improve a shared process before a client deliverable while keeping the deal-team lead informed. The interviewer should hear initiative paired with judgment, not unofficial authority.
7. Describe a Time You Made a Mistake in Your Financial Work and How You Handled It
Choose an error that was real, contained, and recoverable. The interviewer is assessing accuracy, judgment, ownership, and integrity through your response, not the size of the mistake. Explain how you found it, who needed to know, what you corrected, and what changed afterward.
Consider a cash-reconciliation example in which you treated a bank timing difference as an ordinary deposit in transit. When the deposit failed to clear, you traced the transaction and found it had been recorded twice in the ledger. A strong STAR answer covers the immediate disclosure, correction of the entry, and documentation of the fix. Add a review rule for unresolved timing differences to show that the incident led to a practical control.
A loan calculation can provide a different example. You might have applied the wrong day-count convention, identified the impact during review, informed your manager, corrected the general-ledger entry, and documented the proper method for future users. State what could have been misstated or delayed, rather than claiming the issue was harmless.
Build the answer around this sequence:
- Own the action: Describe exactly what you did incorrectly. Do not blame the system or another person.
- Explain the consequence: Connect the error to reporting integrity, a forecast, a client communication, or a decision that could have been affected.
- Escalate promptly: Name the manager, reviewer, controller, or process owner you notified, and explain what you confirmed before making the correction.
- Prevent recurrence: Mention the checklist, review rule, procedure update, training step, or reconciliation change you introduced.
A mistake becomes evidence of maturity when you show the full response, not just the correction.
Avoid stories involving intentional concealment, repeated negligence, or disregard for compliance. A missed follow-up, incorrect assumption, or incomplete review can demonstrate learning when you address the risk directly and show the control that now catches it.
Tailor the lesson to the role. In investment banking, emphasize transaction accuracy, review discipline, and escalation before a client deliverable. In corporate finance, focus on reporting integrity and the effect on management decisions. In FP&A, explain how you strengthened assumption review or forecast checks. In asset management, show how you protected the reliability of research, valuation inputs, or client communication. Keep the result measurable when your experience supports it, but do not invent precision.
8. Tell Me About a Time You Had to Balance Competing Priorities or Stakeholder Requests
Interviewers use this question to assess judgment under competing demands. A strong answer shows how you weighed deadline, financial risk, decision impact, and stakeholder expectations, then made the trade-off visible.
A close-period example might involve a VP of Sales requesting a commission analysis, a controller needing a reconciliation before a board meeting, and the close still requiring completion. Clarify the required standard for each item. If the commission analysis only needs a directional view, confirm that scope. Estimate the work, rank requests by fixed deadline and business risk, then propose specific delivery times.
Use a short decision record to make the reasoning easy to follow:
- Identify the requests: State who asked, what each person needed, and the expected timing.
- Set the output standard: Separate a complete analysis from a directional view or progress update.
- Choose the order: Consider external deadlines, reporting risk, decision impact, and dependencies.
- Offer a trade-off: Suggest a revised deadline, partial output, or staged delivery.
- Confirm agreement: Tell each stakeholder what will be delivered and when.
For example, a staff accountant may have an external client review that afternoon, a CFO requesting variance analysis for a later budget meeting, and routine expense coding from a senior colleague. Complete the client material first because its deadline is fixed and external. Tell the CFO when the variance analysis will be ready, and confirm that the coding can wait. The result matters, but the communication demonstrates control of the workload.
Avoid saying, “I worked on everything at once.” That answer provides no basis for prioritization. Explain what you deferred, why you deferred it, and how you protected quality on the work with the greatest consequence.
Tailor the evidence to the role. In investment banking, discuss client deliverables, transaction accuracy, and senior-review cycles. In corporate finance, connect the decision to close, audit, or treasury dependencies. In FP&A, focus on executive requests, forecast assumptions, and the timing of management decisions. In asset management, address client reporting, research deadlines, valuation inputs, or risk-sensitive outputs. Include a measurable result when your experience supports one, without manufacturing precision.
Build a Bank of Proof, Not Scripts
Finance behavioral interviews reward recall under pressure, but memorizing eight perfect speeches usually makes delivery worse. Candidates lose their place when the interviewer changes the wording, asks a follow-up, or probes for the specific action behind a polished sentence. Build a small bank of authentic stories that can flex across questions instead.
Start with two or three experiences that contain several kinds of evidence. A deadline story may also demonstrate prioritization, communication, and ownership. An error story may support questions about integrity, judgment, and process improvement. A disagreement story may show technical rigor, stakeholder management, and the confidence to challenge an assumption respectfully.
Finance interview guidance commonly groups behavioral prompts into teamwork, leadership, conflict, failure, and creativity, giving candidates a practical way to map examples from internships, coursework, or part-time work to role expectations (the CFI interview ebook). Use those categories as a starting point, then add the finance-specific evidence employers need, including accuracy, risk awareness, commercial judgment, and compliance discipline.
Rehearse the evidence
For every story, write a short prompt rather than a script:
- Situation: What was happening, and why did it matter?
- Task: What were you responsible for?
- Action: What did you personally decide, build, communicate, or change?
- Result: What changed, and how can you demonstrate it?
- Learning: What would you repeat or do differently?
Quantify outcomes when the figure is verified and relevant. Finance interview guidance recommends expressing results with percentages or dollar amounts rather than vague praise (Kaplan's STAR guidance). Modern preparation examples also emphasize naming the baseline and the before-and-after result, such as reducing a reporting cycle from five days to two or reducing forecasting time by twenty percent per quarter (Randstad's finance interview preparation guide). Don't borrow those outcomes for your own story. Use them only as a model for the level of specificity your verified experience should provide.
The hiring environment is moving toward evidence-based assessment. A finance-hiring benchmark cited that 80% of finance employees prefer skills-based hiring, 12 percentage points above the industry-wide average (TestGorilla's finance behavioral interview guidance). That makes resume-grounded preparation more useful than generic personality answers. Panels need to compare how candidates demonstrate communication, problem-solving, resilience, and risk judgment.
Your delivery also deserves practice. Candidates can know their stories and still struggle with anxiety, eye contact, confidence, or retrieving details under interview pressure. A 2025 study of neurodivergent students and alumni identified anxiety or nervousness, intimidation, lack of confidence, and lack of practice among reported interview barriers (the study in SAGE Journals). Rehearse aloud, record yourself, shorten long setup paragraphs, and practice answering follow-up questions without losing the result.
Qcard can serve as an optional preparation aid for resume-grounded talking points, practice, pacing, and natural delivery. Its practice tools include finance questions and STAR-style behavioral prompts, while its real-time support is designed around concise memory cues rather than memorized scripts. Use any tool as a prompt for your verified experience, not as a substitute for knowing what you did.
Before the interview, check each story for three things. Your action must be unmistakable. Your result must be supported by a real figure or a clear qualitative outcome. Your learning point must show how the experience changed your future behavior. That combination turns finance experience into evidence interviewers can trust.
Key Takeaways
- Behavioral questions carry more weight in finance than most candidates expect — one investment-banking guide estimates 30–50% of interviews, with Goldman Sachs around 60% behavioral and J.P. Morgan investment banking around 66% behavioral based on 107 candidate reports, which means technical fluency alone won't carry a loop.
- Prioritization logic beats effort in every deadline story — "I worked hard" tells an interviewer nothing about how you protect quality under pressure, while identifying the largest and highest-risk balances first, dividing remaining work systematically, and giving stakeholders a concise status update before the deadline becomes a crisis demonstrates the judgment finance teams actually hire for.
- Error and mistake stories should end with a specific control, not a vague lesson — adding a second-level review for higher-value reimbursements, a review rule for unresolved timing differences, or documented day-count methodology shows the incident produced a durable process change, while claiming an issue was harmless or blaming a system undermines the integrity signal these questions exist to test.
- Ownership stories need visible boundaries — saying "I fixed a problem nobody else was handling" sounds territorial and suggests weak collaboration, while naming the process owner, confirming permission before acting, specifying exactly what you built, and stating what remained with the other team demonstrates initiative paired with governance judgment.
- Build two or three flexible stories rather than eight memorized scripts — a deadline story can also demonstrate prioritization, communication, and ownership; an error story can support integrity, judgment, and process improvement; and a disagreement story can show technical rigor plus stakeholder management, which is why candidates who memorize separate speeches lose their place the moment an interviewer changes the wording or asks a follow-up.
Qcard helps finance candidates prepare with resume-grounded talking points, behavioral practice, and coaching for pacing and answer length. Build your evidence bank without memorizing scripts, then visit Qcard to practice turning real finance experience into concise, natural answers.
Ready to ace your next interview?
Qcard's AI interview copilot helps you prepare with personalized practice and real-time support.
Try Qcard Free